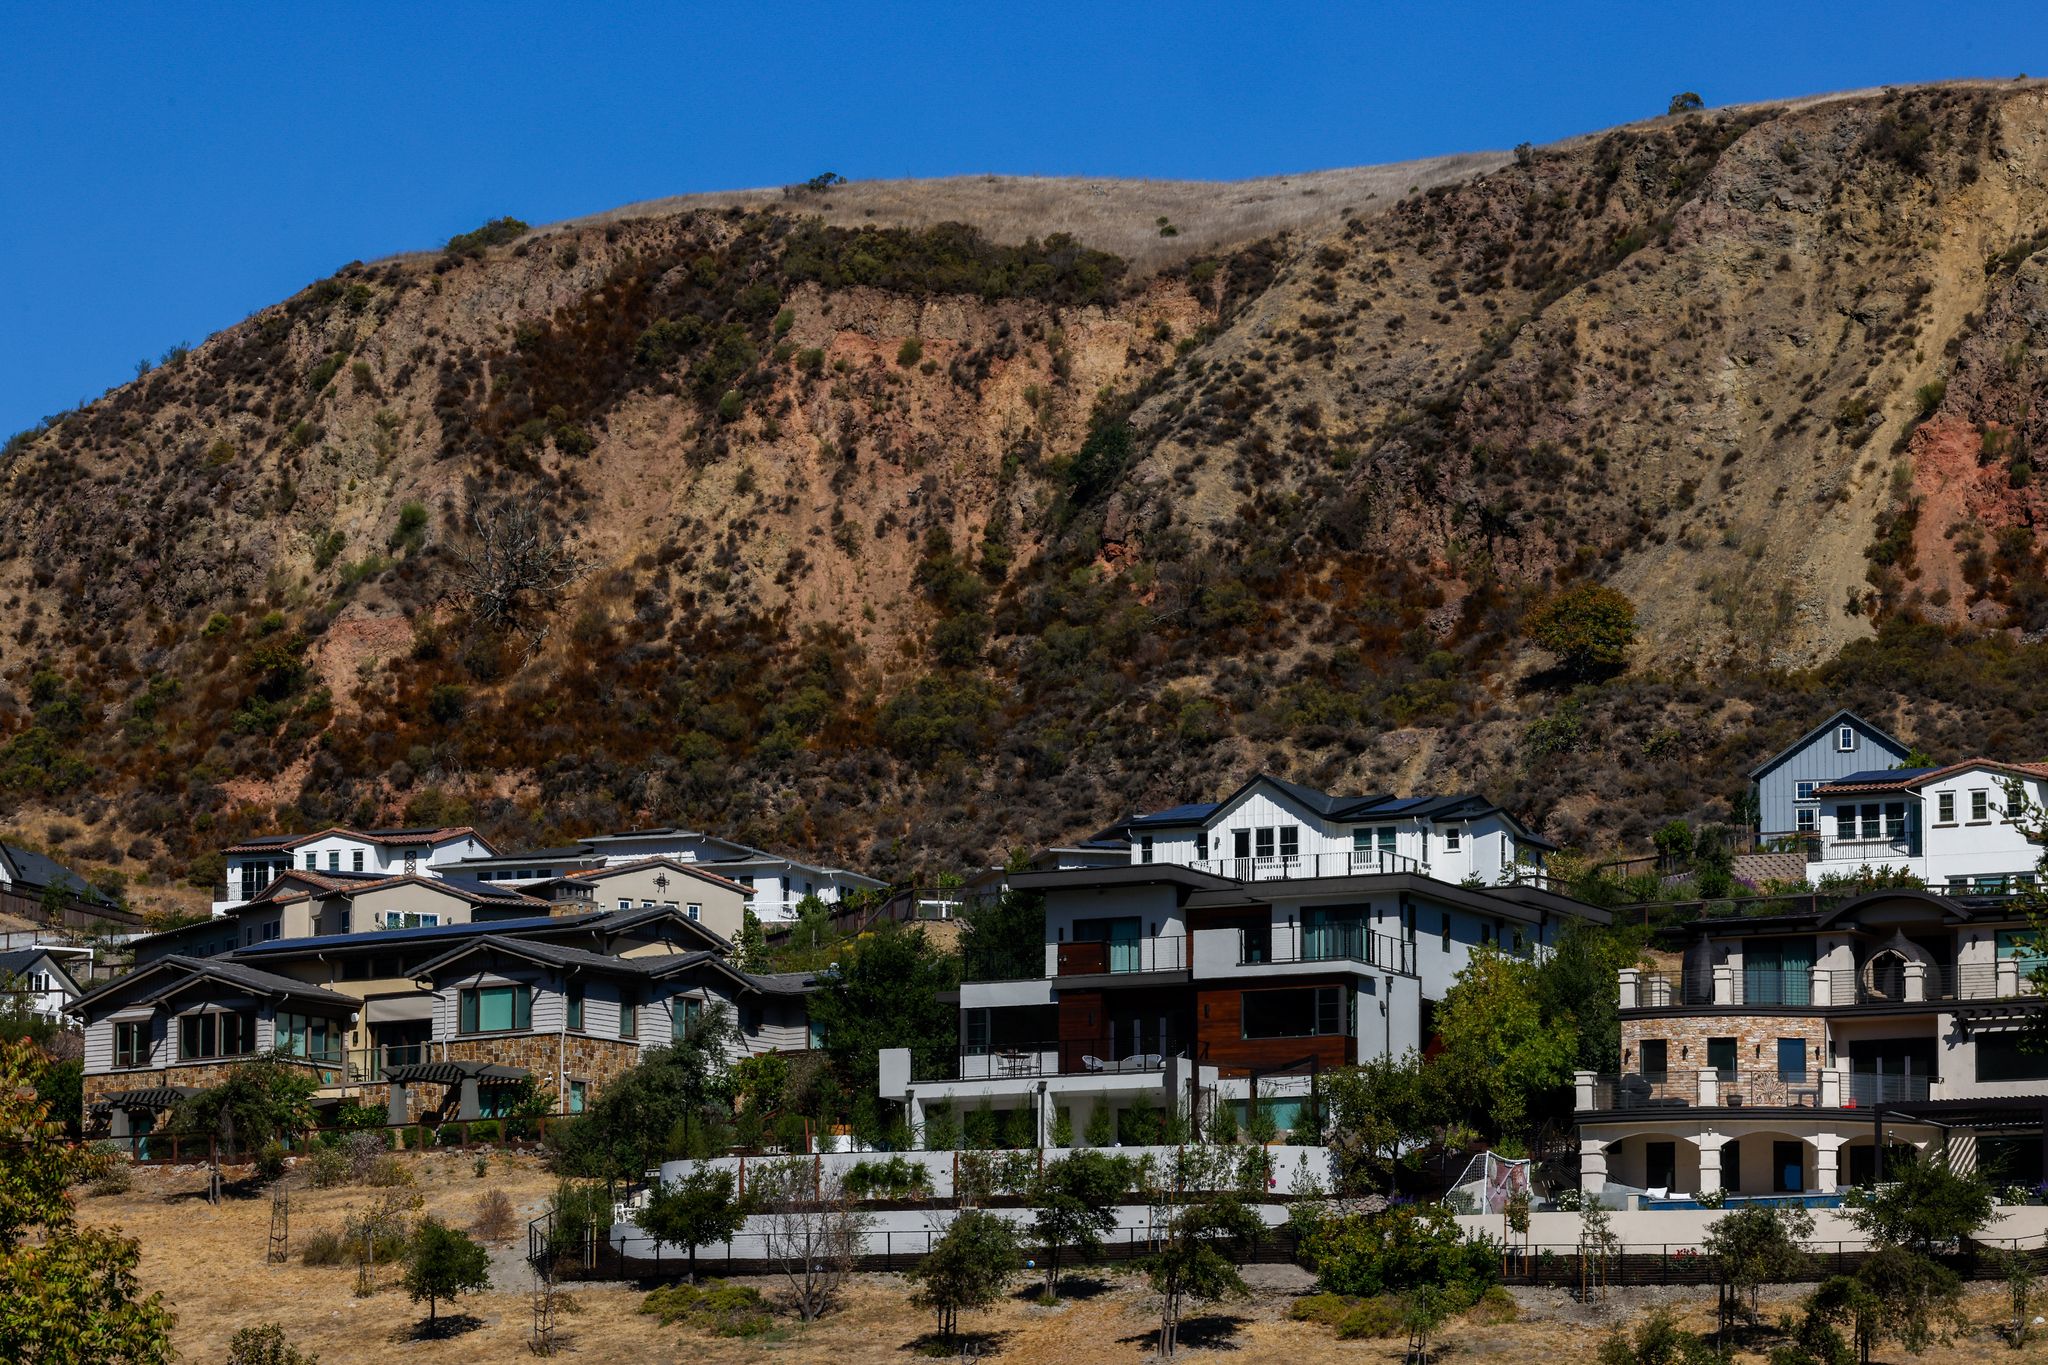
Farmers to Write 5,500 New California Home Insurance Policies with 1.5% Rate Increase
For homeowners across the San Francisco Bay Area, the arrival of an insurance renewal notice has shifted from a mundane administrative task to a moment of genuine anxiety. Whether you’re tucked into a Victorian in Noe Valley or managing a mid-century modern in the East Bay hills, the stability of the California homeowners’ insurance market has felt precarious for years. The latest development—a deal involving Farmers Insurance, the state’s second-largest home insurer—highlights the delicate, often frustrating dance between corporate solvency and consumer protection in a state plagued by climate volatility.
The core of the news is a strategic compromise. Farmers Insurance has agreed to write more than 5,500 new home insurance policies across California. In the current climate, where several major carriers have simply stopped taking new applicants, this is ostensibly a win for consumers. However, this “olive branch” comes with a price tag: an overall rate increase of 1.5%. While a 1.5% average might sound negligible on a spreadsheet, the reality for the individual homeowner is often far more volatile. Some policyholders will see their premiums remain stable, while others—particularly those in higher-risk zones—could see spikes that far exceed that average.
The High Cost of the “Insurance Desert”
To understand why a modest rate hike in exchange for new policies is even a headline, one has to look at the emerging “insurance deserts” forming across the West Coast. For a long time, the California Department of Insurance (CDI) has acted as a strict gatekeeper, limiting how much insurers can raise rates to keep housing affordable. But this regulatory ceiling has created a secondary crisis: insurers are losing money on California policies due to the skyrocketing cost of rebuilding after catastrophic wildfires and the general inflation of construction materials.
When giants like Farmers or State Farm restrict new business, it pushes homeowners toward the California FAIR Plan. For those unfamiliar, the FAIR Plan is the insurer of last resort—a state-mandated system that provides basic fire coverage when no one else will. The problem is that FAIR Plan policies are often significantly more expensive and offer far less comprehensive coverage than a standard policy. This creates a socio-economic divide where only the wealthiest can afford the “last resort” or pay the surging premiums of the remaining private carriers, while middle-class families find themselves under-insured or priced out of their own neighborhoods.
In the Bay Area, this is particularly acute. The sheer valuation of real estate from San Jose to Sausalito means that “replacement cost” is an astronomical figure. If a home in the Berkeley Hills burns, the cost to rebuild to current California building codes is vastly higher than it was a decade ago. This gap between the insured value and the actual cost to rebuild is a ticking time bomb for local equity.
The Ripple Effect on the Local Housing Market
The instability of insurance doesn’t just affect the monthly budget; it’s beginning to warp the real estate market. We are seeing a trend where potential buyers are becoming hesitant to purchase homes in “high-fire-severity zones” not because they fear the fire itself, but because they fear they won’t be able to secure a mortgage without affordable insurance. Lenders generally require a valid homeowners’ policy to close a loan. If a buyer is forced into a prohibitively expensive FAIR Plan policy, the debt-to-income ratio shifts, potentially killing the deal.
This creates a second-order effect: a stagnation of property values in some of the most scenic parts of the region. When the cost of maintaining a home becomes unpredictable, the “dream home” in the redwoods becomes a financial liability. It’s a systemic shift that requires more than just a few thousand new policies to fix; it requires a fundamental rethinking of how we value risk in a warming world. For more insights on managing these shifts, you might explore our guide on navigating California property laws to better understand your rights.
Navigating the New Insurance Landscape
Given my background as an executive geo-journalist focusing on urban resilience and local economics, it’s clear that relying on a single “captive” agent—someone who only sells policies for one company—is no longer a viable strategy in the Bay Area. The market is too fragmented and the rules are changing too quickly. If you are facing a rate hike or have been denied coverage, you need a diversified professional support system.
If this trend impacts you in the San Francisco Bay Area, here are the three types of local professionals Make sure to engage to protect your assets:
- Independent Insurance Brokers
- Unlike captive agents, independent brokers have access to a wide array of carriers, including smaller surplus lines insurers that might have a higher appetite for California risk. When vetting a broker, look for those who specialize in “hard-to-place” properties and who can provide a side-by-side comparison of the California FAIR Plan versus private alternatives. They should be able to explain the difference between “Actual Cash Value” and “Replacement Cost” in the context of current local labor rates.
- Home Hardening & Mitigation Specialists
- Insurance companies are increasingly offering discounts—or requiring prerequisites—based on “home hardening.” These are specialists who install ember-resistant vents, clear defensible space according to CAL FIRE standards, and upgrade roofing materials. Look for contractors who are certified in wildfire mitigation and can provide a formal report or certification that you can submit to your insurer to potentially negotiate a lower premium.
- Real Estate Asset Strategists
- For those with significant equity, a strategist or a specialized real estate attorney can help you understand how to structure your holdings to mitigate risk. This includes auditing your current policy for over-insurance (paying for coverage you don’t need) or identifying gaps that could lead to a denied claim. Look for professionals who have a deep understanding of the specific zoning and environmental hazards of the Bay Area’s various micro-climates.
The deal struck by Farmers is a temporary bandage on a deep wound. While the addition of 5,500 policies is a start, the broader trend suggests that the era of cheap, easy home insurance in California is over. The goal now is not just to find a policy, but to build a resilient home and a robust financial strategy that can withstand the volatility of the market.
Ready to find trusted professionals? Browse our complete directory of top-rated home insurance experts in the San Francisco Bay Area today.