
Unprecedented Impact of Petrochemicals and Commodities on the Global Economy
Walking through the Energy Corridor in Houston, it is easy to experience a sense of insulated strength. As the petrochemical capital of the world, this city is the heartbeat of the Western Hemisphere’s chemical production. But while the local skyline remains steady, the global supply chain is currently experiencing a seismic shift that is starting to ripple through the Gulf Coast. The recent escalation of the war in Iran and the effective closure of the Strait of Hormuz have created a geopolitical choke point that is doing more than just spiking oil prices; it is triggering what analysts are calling an “everything crisis.” For those of us in Houston, the perspective is unique—we are sitting on the very resources that the rest of the world is suddenly desperate to secure, yet we are not immune to the inflationary fallout that follows when global manufacturing falters.
The Ethane Advantage and the Naphtha Nightmare
To understand why Houston finds itself in a paradoxical position, one has to look at the chemistry of production. As Jim Fitterling, the chair and CEO of Dow, recently noted during the CERAWeek by S&P Global conference here in Houston, there is a stark divide between the West and the East. Most commodity petrochemical plants in the United States rely on natural-gas-derived ethane as their primary feedstock. Because ethane is sourced domestically, the blockade of the Strait of Hormuz doesn’t stop the flow of raw materials into our local plants.
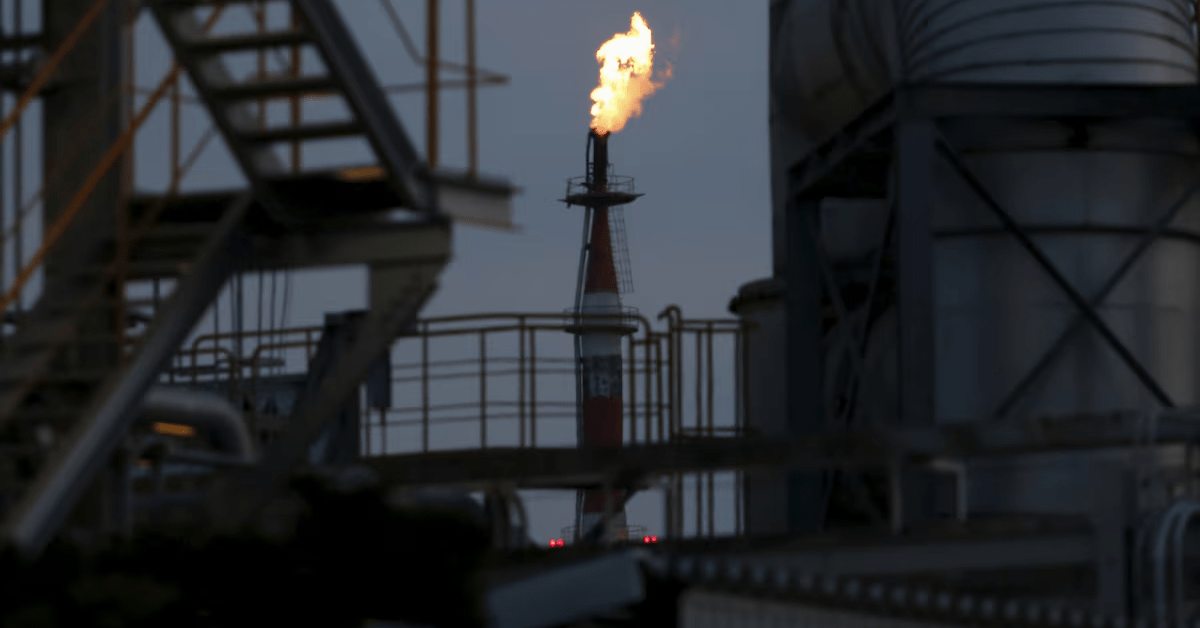
Yet, the situation in Asia and much of Europe is dire. These regions rely heavily on crude-oil-based naphtha. With nearly half of Asia’s naphtha supplies flowing through the Strait of Hormuz, the blockade has effectively severed the lifeline for a massive portion of the global chemical industry. We are seeing a scenario where almost 20% of global petrochemical capacity is blocked. This isn’t just a corporate inconvenience; it is a systemic failure. Kurt Barrow of S&P Global Energy has already highlighted that many Asian plants are declaring force majeure—a legal declaration that they cannot fulfill their contracts—because they simply cannot receive the naphtha required to operate.
This creates a “K-shaped” economic trend. On one side of the K, Western producers, led by the U.S., maintain their feedstock. On the other, Eastern manufacturers are crashing. While we might not see empty shelves at a local Home Depot immediately, the lag time is inevitable. Chemicals are the invisible building blocks of nearly every consumer excellent. When the Asian manufacturing engine stalls, the cost of everything from plastic resins to synthetic rubbers climbs globally, regardless of where the raw ethane is sourced.
From Petrochemicals to the “Everything Crisis”
The terrifying reality of this shortage is how quickly it translates from a boardroom discussion about “feedstocks” to a crisis in daily life. We are seeing a domino effect where the lack of basic petrochemicals is impacting critical healthcare and consumer staples. In Japan, there are legitimate fears that patients requiring hemodialysis may face shortages of the plastic medical tubes essential for their treatment. In Malaysia, the production of medical gloves is under threat because of a dearth of petroleum byproducts needed for rubber latex.
The shortage extends into the most mundane items. In Taiwan, the government has had to establish hotlines for manufacturers who have run out of plastic, and rice farmers are warning of price hikes because they lack the vacuum-sealed bags necessary for preservation. In South Korea, the scarcity of plastic has led to the panic-buying of government-regulated trash bags. This is the “everything crisis” in action: it spills into beer, noodles, chips, toys, and cosmetics almost instantaneously. For a global hub like Houston, which manages the logistics for these materials, the pressure to fill the void left by Asian production will be immense, but the global logistics network is not designed for an instantaneous rewind.
The Collision of Oversupply and Sudden Shock
Adding a layer of complexity to this is the structural state of the industry prior to the war. According to Lee Andrew Fagg of Wood Mackenzie, the petrochemical sector was already reeling from a crisis of oversupply, driven largely by aggressive capacity expansion in China. This overcapacity had pushed margins to historic lows and forced many plant closures. Now, the industry has swung from a state of “too much” to “not enough” in a matter of weeks. This volatility makes it nearly impossible for companies to plan their procurement cycles, leading to the 250- to 275-day “unwind” period that Fitterling warned about. We are not looking at a quick fix; we are looking at a prolonged period of instability that will likely fuel inflation through the end of 2026.
Navigating the Fallout in Houston
Given my background in analyzing geo-economic trends, Houston businesses—particularly those in construction, aerospace, and automotive manufacturing—need to pivot their procurement strategies immediately. The reliance on “just-in-time” delivery from Asian partners is now a liability. If your operations depend on polymers, rubber, or polyester, you are now operating in a high-risk environment where “force majeure” is the new norm.
If this trend impacts your business or household in the Houston area, you cannot rely on standard retail channels. You need specialized guidance to navigate the current volatility of the industrial materials market. Here are the three types of local professionals Make sure to be consulting right now:
- Supply Chain Diversification Consultants
- Look for consultants who specialize in “near-shoring” or “friend-shoring.” You need experts who can facilitate you transition your sourcing from naphtha-dependent Asian markets to ethane-based North American suppliers. Ensure they have a proven track record of auditing secondary and tertiary suppliers to ensure there are no hidden dependencies on the Strait of Hormuz.
- Industrial Procurement Specialists
- You need professionals who understand the legalities of force majeure and the nuances of commodity hedging. The ideal specialist will have deep connections with Gulf Coast refineries and chemical plants, allowing you to secure raw material contracts before the “everything crisis” hits the domestic retail level.
- Commercial Inflationary Risk Managers
- As petrochemical prices spike, your overhead will climb. Seek risk managers who can perform a “materiality audit” on your product line. They should be able to identify which of your components are most vulnerable to petrochemical shortages and help you implement price-adjustment clauses in your client contracts to protect your margins.
Ready to find trusted professionals? Browse our complete directory of top-rated supply chain consultants experts in the houston area today.