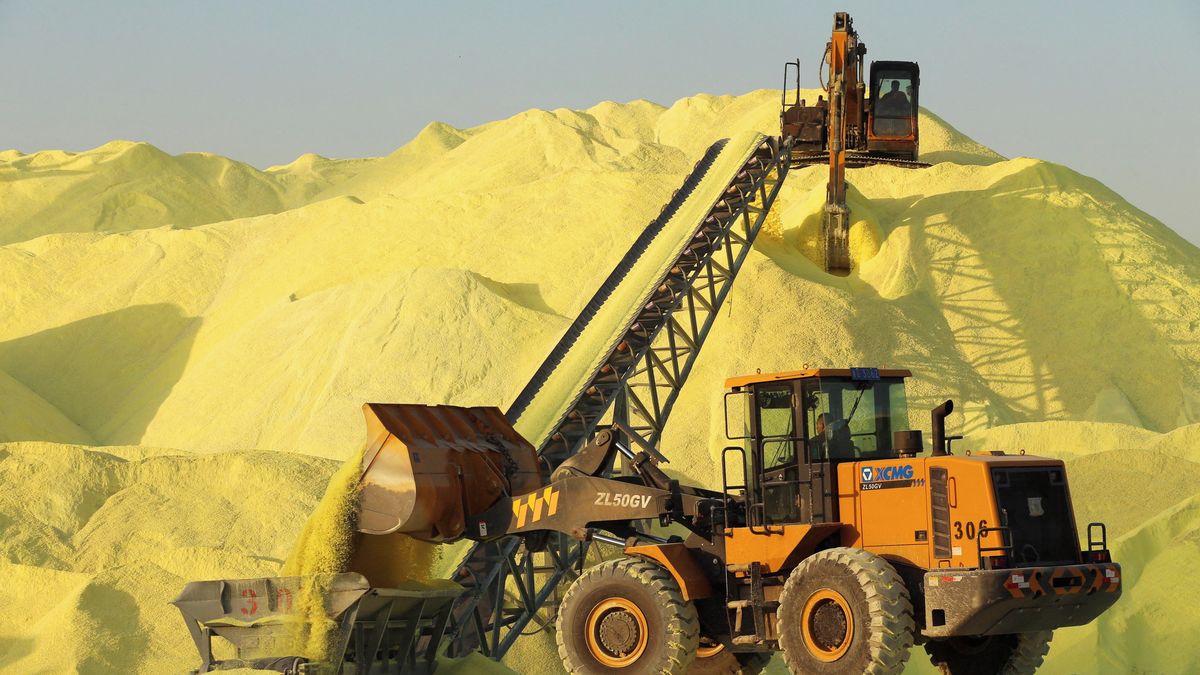
Sulfur Prices Surge: Impact on Fertilizer, Metals & Global Supply Chains
Sulfur Prices Surge Amidst Iran Conflict and Growing Demand
The price of sulfur is experiencing a significant increase, driven by escalating tensions in Iran and a corresponding rise in demand, particularly for fertilizer production. As of the end of last week, sulfur prices in Africa reached $700 per ton (approximately 15,000 Czech crowns), according to data published in the Financial Times. China is also seeing substantial price hikes, closing the week at 4,750 yuan per ton (roughly 14,630 Czech crowns), up from 3,800 yuan at the end of February, as reported by Trading Economics. This surge impacts a range of industries, from agriculture to metal refining, and highlights the vulnerability of global supply chains to geopolitical instability.
A Gradual Climb Accelerated by Conflict
Even as prices began to rise in the autumn, increasing from 2,500 yuan per ton in October to 4,000 yuan by year-end, the recent escalation is directly linked to the conflict in the Middle East. Between February and March, prices also rose in Europe, reaching $410 per ton (8,700 Czech crowns) and continuing to climb. Current prices are nearing or exceeding levels seen during the COVID-19 pandemic, according to data from Imarc. The situation is particularly concerning for countries reliant on imports from the Persian Gulf region.
China’s Dependence and the Spring Planting Season
The South China Morning Post has highlighted China’s vulnerability, noting that the nation relies on imports for 47 percent of its sulfur supply, with half of those imports originating in countries within the Persian Gulf. The ongoing conflict is restricting the flow of sulfur into China at a time when demand is increasing due to the approaching spring planting season. This timing exacerbates the problem, as sulfur is a critical component in the production of fertilizers essential for crop growth.
Sulfur’s Role in Agriculture and Beyond
Sulfur is a key ingredient in ammonium sulfate, a significant nitrogen-based fertilizer containing a high sulfur content. Crops like potatoes, onions, turnips, and rapeseed all require sulfur for healthy growth. Sulfuric acid is used in the production of phosphate fertilizers, such as superphosphate, which is vital for flowering and fruit development. However, the impact extends beyond agriculture. Sulfur is also crucial in the extraction of metals like nickel and copper, adding another layer of complexity to the supply chain disruption.
The Strait of Hormuz and Global Supply
The disruption to shipping through the Strait of Hormuz is having a severe impact on the sulfur market. Approximately 25 percent of global sulfur production, around 84 million tons, originates in the Middle East. Countries around the Persian Gulf account for 45 percent of global sulfur exports, as reported by the Financial Times. This supply is currently unavailable, as Kuwait has ceased exporting both oil and sulfur, and other Middle Eastern producers are following suit. Even when sulfur is available, securing transportation is proving difficult. “We can’t order transport, nobody wants to do it,” stated Clive Murray of London Commodity Brokers.
Widespread Disruptions and Impacted Companies
At least 44,000 companies have not received ordered sulfur deliveries, according to analytics group Dun & Bradstreet. India and China are among the most affected nations. The situation is compounded by the fact that the Middle East is also a significant source of urea and phosphates, further essential fertilizer components. The price of urea has risen to $710 per ton, a 45 percent increase since the start of the conflict.
Nickel and Copper Production at Risk
Indonesia, which produces over half of the world’s mined nickel, is heavily reliant on sulfur imports from the Middle East, sourcing 75 percent of its needs from the region, according to a Reuters report. Current sulfur reserves in Indonesian facilities are sufficient for only one to two months. Prior to the conflict, the cost of sulfur already accounted for half of the operating expenses of Indonesian HPAL nickel production facilities on Sulawesi Island, according to analyst Marco Martins of Project Blues.
Indonesian nickel producers are competing with South African copper miners for limited sulfur supplies. Southern Africa currently holds approximately 900,000 tons of sulfur in storage, enough for several weeks. The Democratic Republic of Congo alone imported between 1.3 and 1.4 million tons last year for copper extraction.
Limited Alternatives and Uneven Impact
While microchip manufacturers have relatively low sulfur consumption and can potentially source it from alternative suppliers, fertilizer producers face a more significant challenge due to the sheer volume of sulfur required. The largest fertilizer manufacturers consume 60 percent of global sulfur production, making it difficult to find substitutes. This scarcity will inevitably translate into higher fertilizer prices, disproportionately impacting impoverished, agriculturally-dependent countries already struggling with food security.
The Future of Sulfur Supply and Pricing
The Financial Times notes that a significant price decrease is unlikely, as sulfuric acid is also essential in the production of batteries, particularly those used in electric vehicles. Demand from this sector will continue to support prices. The situation underscores the interconnectedness of global supply chains and the potential for geopolitical events to trigger widespread economic consequences.
Looking ahead, monitoring shipping routes through the Strait of Hormuz and the potential for increased production from alternative sources will be crucial. However, given the current geopolitical climate and the essential role of sulfur in multiple industries, sustained price volatility and supply chain disruptions appear likely in the near term.